Every counterparty from every angle.
Credit risk, compliance risk and the business case for a counterparty come together, with a recommendation based on your policies, all in a single platform.
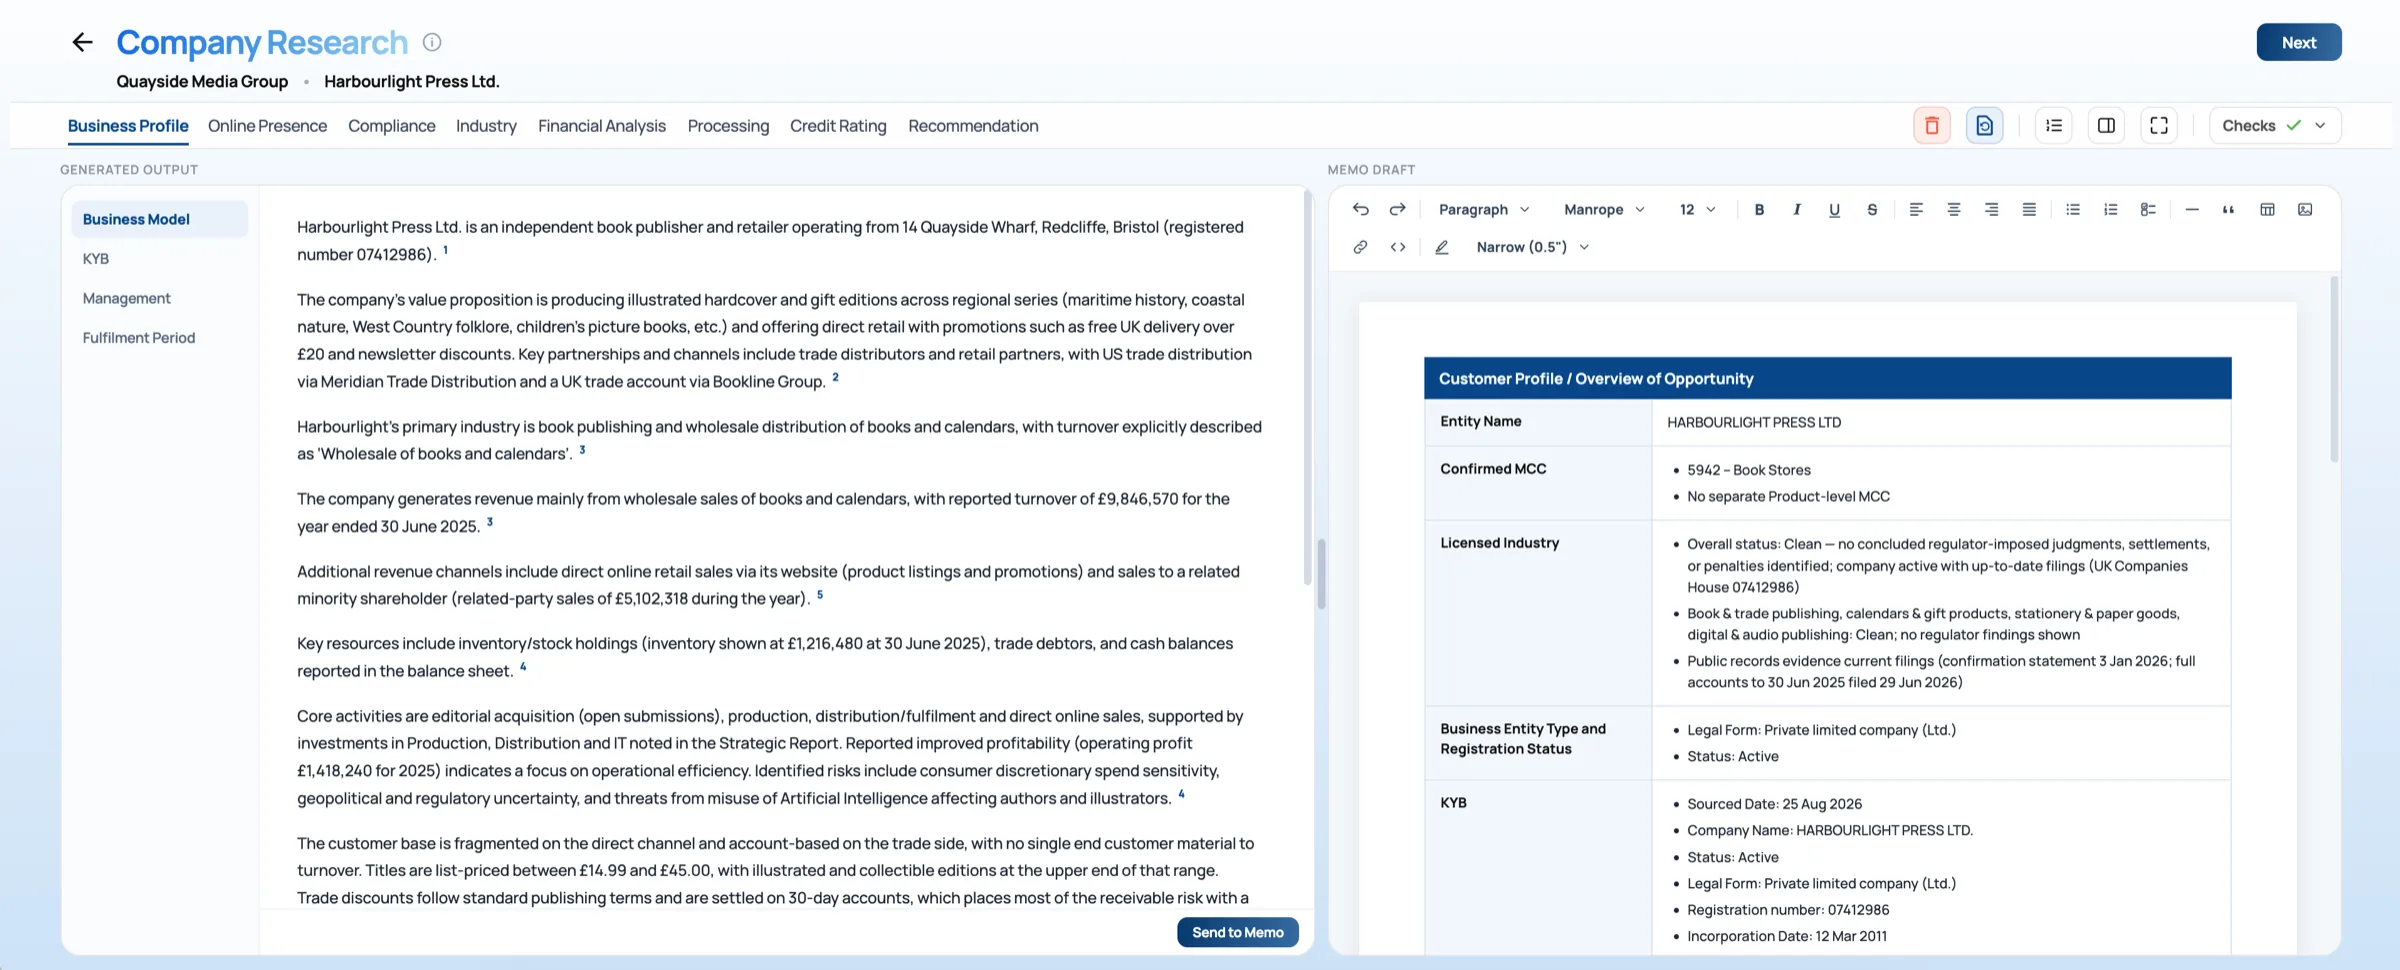
Every module’s research and analysis in full, with the recommendation at the end.
Findings summarised into your own template and editable in place.
Credit, compliance and commercial now fully aligned.
- The CRM hands over the business case.
- Credit and compliance modules sit side by side.
- The recommendation carries both angles.
The review type decides which modules run.
Fully customisable module selection, so every review only runs what your team needs.
One review covers more than what's humanly possible.
The whole site is scanned, however large it runs: what it sells, where it ships, the fees it charges and the terms it publishes.
Sanctions, enforcement and debarment lists, screened on the entity and on every officer behind it.
News agencies, industry publications and the local press in the counterparty's own market and language.
Blogs, forums, niche publications and major outlets, searched for anything written about the business by anyone other than the business.
Trace any line in the review back to its source.
Revenue reached €1.03B in FY2025, up 12.4% on the year, with EBITDA of€118.3M at an 11.5% margin, which puts net debt / EBITDAR at 2.9×.
The airline sells direct through skylane.ie, where the fare rules, fees and refund terms are published in full.
The parent is Aerline Holdings Ltd in Ireland, under ultimate owner Aerline Capital Partners LP in Jersey. The entity and its officers were screened against 300+ global watchlists with no matches.
Media turned up two items: the winter 2024 schedule disruption, and a ground-handling dispute that has since settled.
Every review applies the policies your teams set.
Memo templates, compliance rules and rating scales, so every review follows existing practices.
- Full review before go-live
- Delayed-delivery reserve sized to advance sales
- Quarterly review
- Advance-sold revenue against cash on hand
- Fuel and lease costs against fares
- Schedule disruption and the refund backlog
Frequently asked questions.
Updated
How does TrustPlus AI automate credit underwriting?
It starts from one set of documents and the CRM record, and runs every module your review type calls for. On the credit side that means financial analysis, industry risk and a credit rating; on the compliance side, KYB and ownership, sanctions and PEP screening and adverse media; and on the commercial side, the sales commentary, pricing, volumes and proposed terms. It then scores the counterparty against your rating scale and drafts the memo in your template with every line cited, so an underwriter opens a finished review in under an hour rather than assembling one over days.
What information does TrustPlus AI analyse during underwriting?
The financial statements you upload, the counterparty's entire website, over 300 global watchlists screened on the company and every officer behind it, thousands of media sources in its own market and language plus millions of other websites, and the business case from your CRM. Which modules run on all of that depends on the review type, whether that is merchant underwriting, corporate credit risk, KYB checks, trade credit, brand risk or something else, and your team sets that selection.
Can TrustPlus AI analyse both quantitative and qualitative credit risk?
Yes. The rating scale your leadership sets carries weighted quantitative and qualitative factors. The ratios from the spread, scored against your appetite thresholds, sit on the quantitative side, and industry risk, ownership, the compliance findings and the business case sit on the qualitative side. The score and the recommendation follow from both.
Can TrustPlus AI generate an underwriting or credit memo?
Yes. Every review ends in a memo drafted in the template your leadership set for that department, whether that is a two-page renewal note or a full committee pack, and every line in it is cited to its source. Your analyst edits it and signs it off, and it can be delivered as a file or over the API.
Can TrustPlus AI apply our bank's credit policy and risk appetite?
Yes. Your leadership sets the memo template for each department, the compliance policy by industry or merchant category along with its review cycle, and the rating scale with its weighted factors, and the ratios are scored against your own appetite thresholds. Every review applies all of that, and if your team works to any other risk policy, you can give it to us and we adopt it into the recommendation.
Can an underwriter review and edit the AI-generated analysis?
Yes. The review arrives as an editable draft with every figure and finding cited, so the underwriter checks it against the sources, changes whatever needs changing and signs it off. Anything that was flagged along the way, whether a watchlist match, an adverse-media item or a ratio outside your appetite, is carried into the draft for the underwriter to decide on.
Can credit analysts verify the sources used by TrustPlus AI?
Yes. Every line carries the source it came from, whether that is the page of the document you uploaded, the page of the counterparty's website, the ownership record, the watchlist or the media item. An analyst, the credit committee or an auditor can open that source and check any statement in the memo against it.
Can TrustPlus AI standardise credit analysis across different underwriters?
Yes. Every review of a given type runs the same modules, is scored against the same rating scale and lands in the same memo template, whoever runs it. Two underwriters looking at similar counterparties end up with reviews a committee can compare line for line.
Can TrustPlus AI integrate with our existing credit systems and CRM?
Yes. It works with any CRM, Salesforce included. The business case comes in from the CRM record with the sales commentary, pricing, volumes and proposed terms, and the result of the review is pushed back to that record so your sales reps see it where they already work. Your other systems can connect over the API, which returns each review with its citations.
Can TrustPlus AI detect early signs of financial deterioration after approval?
It watches for them. Once a counterparty is approved, you set how often it is reviewed again and which modules the re-run covers. New accounts get re-spread, ratios get re-scored against your appetite, screening is refreshed on your schedule, and anything that moved is flagged for your analyst.
Can TrustPlus AI use our own data on the counterparty in the review?
Yes. Anything you already hold on the counterparty can go into the review alongside the documents, so transaction processing data, loan and repayment history, the merchant's or company's replies to your questions over email, and your team's own notes. The modules read it together with everything else, and it feeds the analysis and the memo like any other source.
How is this better than asking ChatGPT, Claude or Copilot to assess a counterparty?
An assistant can only reason about what you paste into it, and when it does go looking it tends to stop after a handful of sources, whether because of a usage limit or because it simply stops searching. It has no access to the watchlists, the media coverage or your CRM record, it does not know your policies or your rating scale, and it cannot show you where a claim came from. TrustPlus AI works through over 300 global watchlists, thousands of media sources and millions of other websites, reads the counterparty's entire website, applies your policies and cites every line, so the review can be checked and defended, and your data is never used to train a model.
Portfolio coverage now goes as deep as you want.
Any review type, on any counterparty, at any point in the relationship, in under an hour, whatever the size of your team.